
Alpha
Portfolio Alpha: How to Measure Skill, Strategy, and Outperformance
What is Alpha?
Alpha is a percentage that shows the extra return, above the S&P 500 benchmark, that a portfolio provides after adjusting for the portfolio's market risk. This gauges the portfolio's effectiveness compared to the benchmark.
What does Alpha tell you?
Alpha measures how much a portfolio has returned above or below what would be expected given its level of market risk. It represents the value added or subtracted by the portfolio manager, independent of broader market movements. A positive Alpha means the portfolio outperformed expectations, while a negative Alpha means it fell short.
Why is Alpha important?
- It isolates the impact of active management by stripping out market-driven returns, showing whether a portfolio manager is genuinely adding value or simply riding market trends.
- It serves as a direct measure of skill, helping investors distinguish between returns that came from smart decision-making versus those that came from taking on more market risk.
- It allows for a more meaningful comparison between portfolios by focusing on performance that cannot be explained by market movements alone.
What is a good Alpha?
Generally, a higher Alpha is better, as it indicates that a portfolio is generating returns above and beyond what the market alone would explain. A positive Alpha means the portfolio manager is adding genuine value through active decision-making, while a negative Alpha suggests the portfolio is underperforming relative to its expected return given its market risk.
What is a typical range for Alpha?
This represents the range of alpha values for the 20-year period ending November 2025, as tracked by RecipeInvesting.com.
- Portfolio Recipes (investable model portfolios)
- Low: -5.5% for Invesco International Dividend (PID)
- High: 9.5% for Adaptive Allocation Portfolio F (t.aaaf)
- Portfolio Ingredients (asset class ETFs)
- Low of -9.5% for iShares MSCI Austria ETF (EWO)
- High of 8.3% for SPDR Gold Shares (GLD)
What do specific Alpha values mean?
- An Alpha of -5% or below means that the portfolio has underperformed by 5% relative to the market and the portfolio's risk level.
- An Alpha of 0% means that the portfolio has performed exactly in line with its expected return given its level of risk, providing no excess return over the benchmark.
- An Alpha of 0.5% means that the portfolio has generated an extra 0.5% annual return, above what we'd expect based on the portfolio's risk level. This indicates a slight positive excess return due to manager skill or other factors.
- An Alpha of 5% or above means that the portfolio has generated 5% more return than expected, given its risk level. This suggests strong performance relative to the market benchmark.
What is the formula for Alpha?
$$\text{Alpha} = R_p - \left(R_f + \beta \cdot \left(R_m - R_f\right)\right)$$
Where:
- Rp = portfolio return
- Rf = risk-free rate
- β = standard deviation of the market
- Rm = market return
How do you calculate Alpha?
Alpha is calculated by taking the portfolio's excess return over the risk-free rate and subtracting the expected excess return based on the portfolio's beta and market performance. Here is how it breaks down step by step:
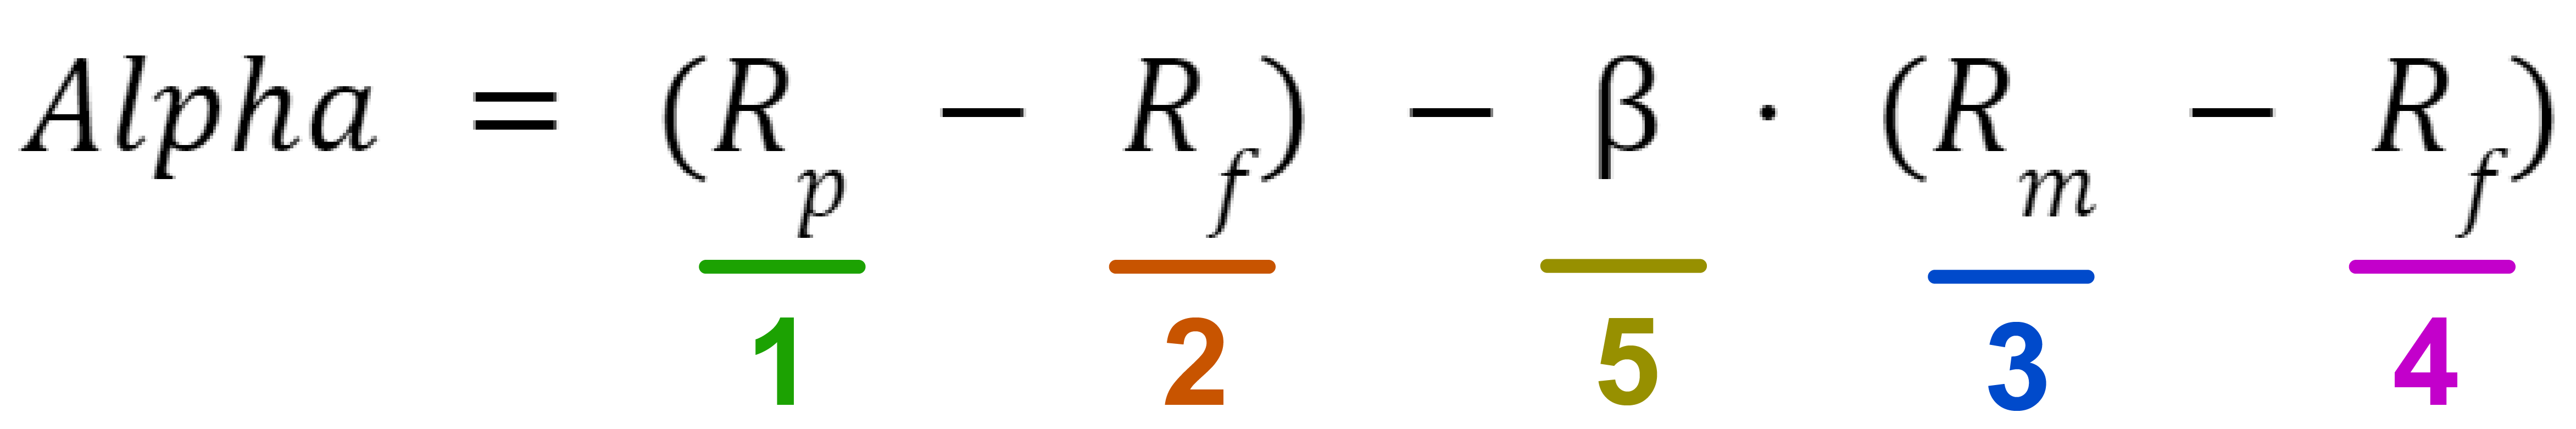
- We start with the portfolio's return (1)
- then we subtract the risk-free return (2) since nobody should get credit for what they can get for free.
- then we subtract the market's return (3), but only the portion above the risk-free rate (4), and this is adjusted up or down based on the portfolio's riskiness compared to the market which is measured by beta (5).
So what's left over is alpha: the extra return that the portfolio has generated above the risk-free return and above what we'd expect based on how risky the portfolio is compared to the overall market.
Can you explain Alpha graphically?
The waterfall chart above breaks down exactly how Alpha is calculated step by step, turning the formula into a visual story.

- The portfolio starts with a total return of 14.8%, but not all of that return counts as skill — some of it is simply compensation for taking on risk or for the passage of time.
- First, we subtract the risk-free rate of 3.1%, stripping out the return anyone could have earned without taking any risk at all, bringing us down to an excess return of 11.7%.
- Then we subtract the expected market return of 2.6% (adjusted by Beta), which represents the portion of the return that can simply be explained by how the market performed and how sensitive the portfolio was to it.
- What's left is the Alpha of 9.1%, the return that cannot be explained by market exposure or the risk-free rate, representing the pure value added by the portfolio manager's decisions.
Alpha is what remains after stripping away everything the market and time could have given you for free. A positive Alpha of 9.1% means the manager genuinely outperformed beyond what market conditions alone would predict.
What is the Alpha for example portfolios?
Alpha for six sample portfolios, over a 20 year period ending Nov 2025.
Portfolio | Ticker or ID | Description | Risk Level | Alpha | Annualized Return |
1-3 Year Treasury Bond fund | SHY | short-term bond fund | very low | 0.3% | 2.0% |
Total Bond Market fund | BND | aggregate bond fund | low | 0.8% | 3.3% |
Balanced Portfolio | s.6040 | 60% stocks, 40% bonds | medium | 0.3% | 8.0% |
S&P 500 fund | SPY | large company stocks | this is "market risk" | 0.0% | 10.9% |
Nasdaq 100 Index fund | QQQ | tech-heavy,large company fund | high | 3.5% | 15.4% |
Adaptive Asset Allocation F | t.aaaf | tactical Portfolio Recipe from RecipeInvesting.com | decent risk/return tradeoff | 9.5% | 14.8% |
What’s the difference between Alpha and Beta?
- Alpha measures the excess return a portfolio generates above what is expected given its market exposure, making it a direct indicator of a manager's skill in outperforming the benchmark.
- Beta measures the portfolio's sensitivity to market movements, providing the risk context that explains how much of the return is driven by market exposure rather than active management.